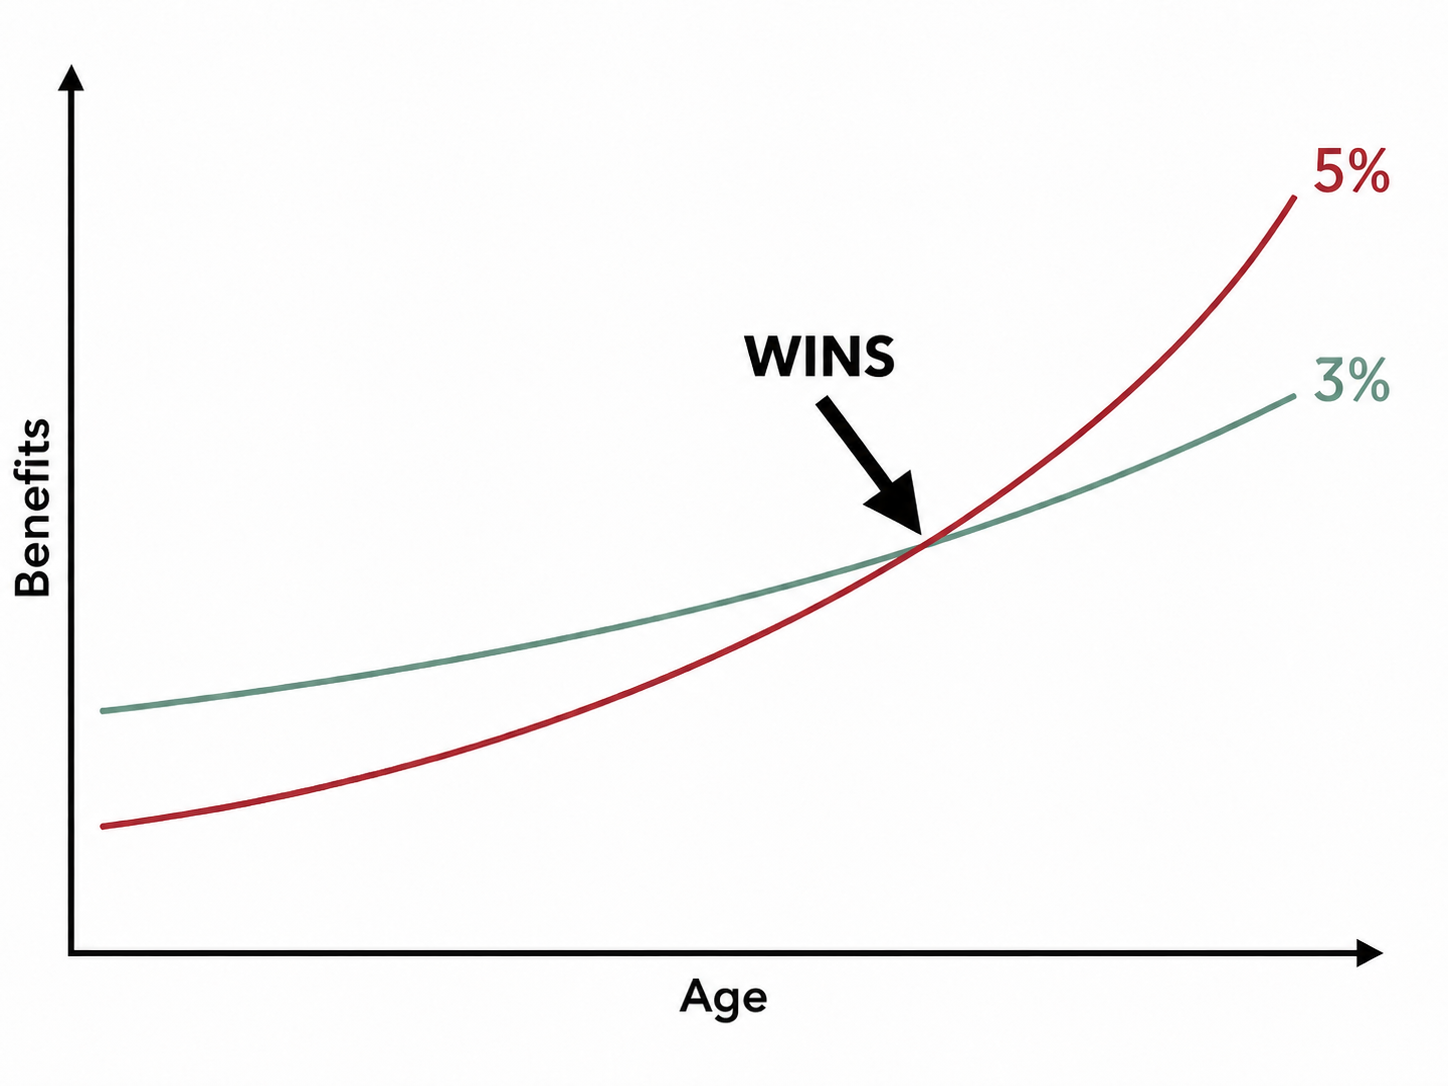

I compared how leading long-term care insurance policies price 3% versus 5% inflation protection. The results show a wide difference in how much value insurers provide for the 5% option.
Study results
I held the premium constant and compared the benefits produced by 3% and 5% inflation protection. The 5% option starts with a lower initial benefit, but grows faster. Once 5% crosses over the 3% line, 5% “wins” because it provides the larger benefit for the same premium.
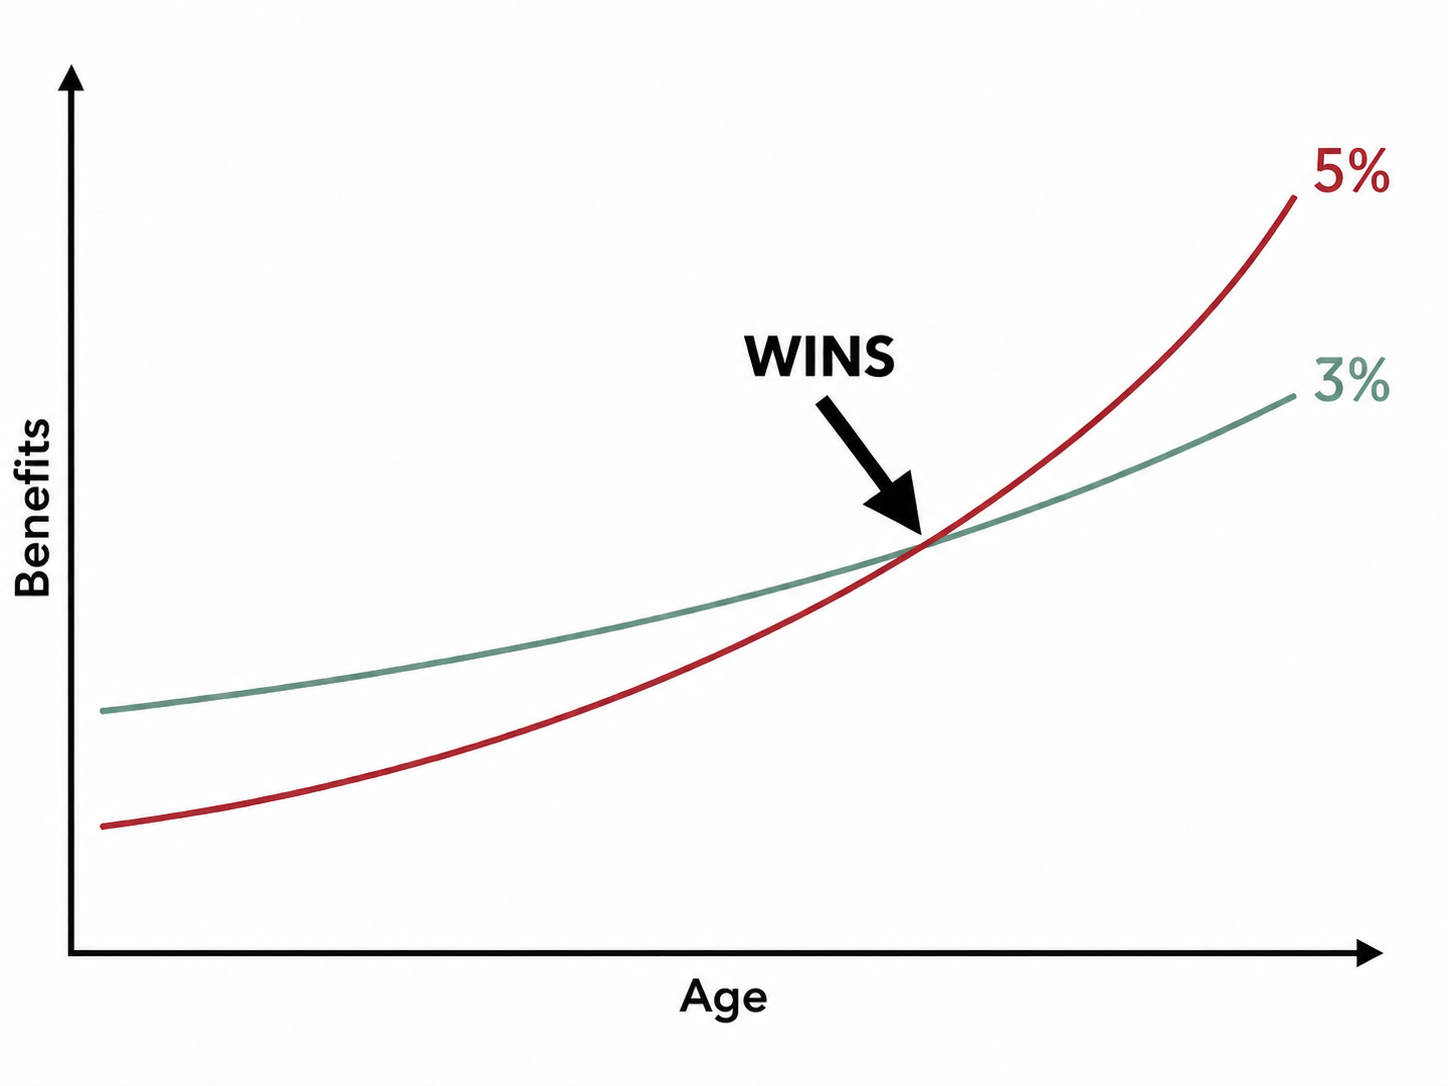
Policies at the top offer the best value for 5% inflation protection because 5% “wins” sooner.
| Policy | Crossover Age |
|---|---|
| OneAmerica Asset Care | 67 |
| Nationwide CareMatters II | 71 |
| Lincoln MoneyGuard Fixed Advantage | 76 |
| Brighthouse SmartCare | 79 |
| Thrivent Standalone | 82 |
| Mutual of Omaha MutualCare | 83 |
| Securian SecureCare IV | 84 |
| NGL HonestLTC | 88 |
This study used a 50-year-old single male in Colorado with 10-pay premiums for hybrids and lifetime pay for traditional policies.
What to know
- Inflation protection: Increases the policy benefit annually to help keep pace with rising care costs.
- Costs keep rising: Long-term care costs have increased about 4.5% annually over the past two decades.
- Pricing varies: Insurers must offer 5% compound inflation protection on tax-qualified policies, but can price it differently.
In practice, 3% compound is the most common option I use. For younger applicants, however, 5% can be worth comparing, particularly with the policies that reached crossover earliest in this study.
Planning implications
This is not a ranking of which policy is best overall. It specifically measures the relative value of 5% inflation protection.
When to raise this with clients
- Clients in their 50s or younger, with decades for benefits to compound
- Clients particularly concerned about increasing long-term care costs
Bottom line
If a client wants 5% benefit growth, start with the policies where 5% “wins” earliest in this study.
Client resources: I publish short videos and articles explaining long-term care concepts for your clients.
Work together: I'm a long-term care specialist. In addition to articles like these, I help financial professionals evaluate coverage options for clients. Reply or schedule time to refer a client or discuss a case.
Best,
Jesse Vickey
Long Term What?
P.S. If this was forwarded to you, sign up to receive future emails.