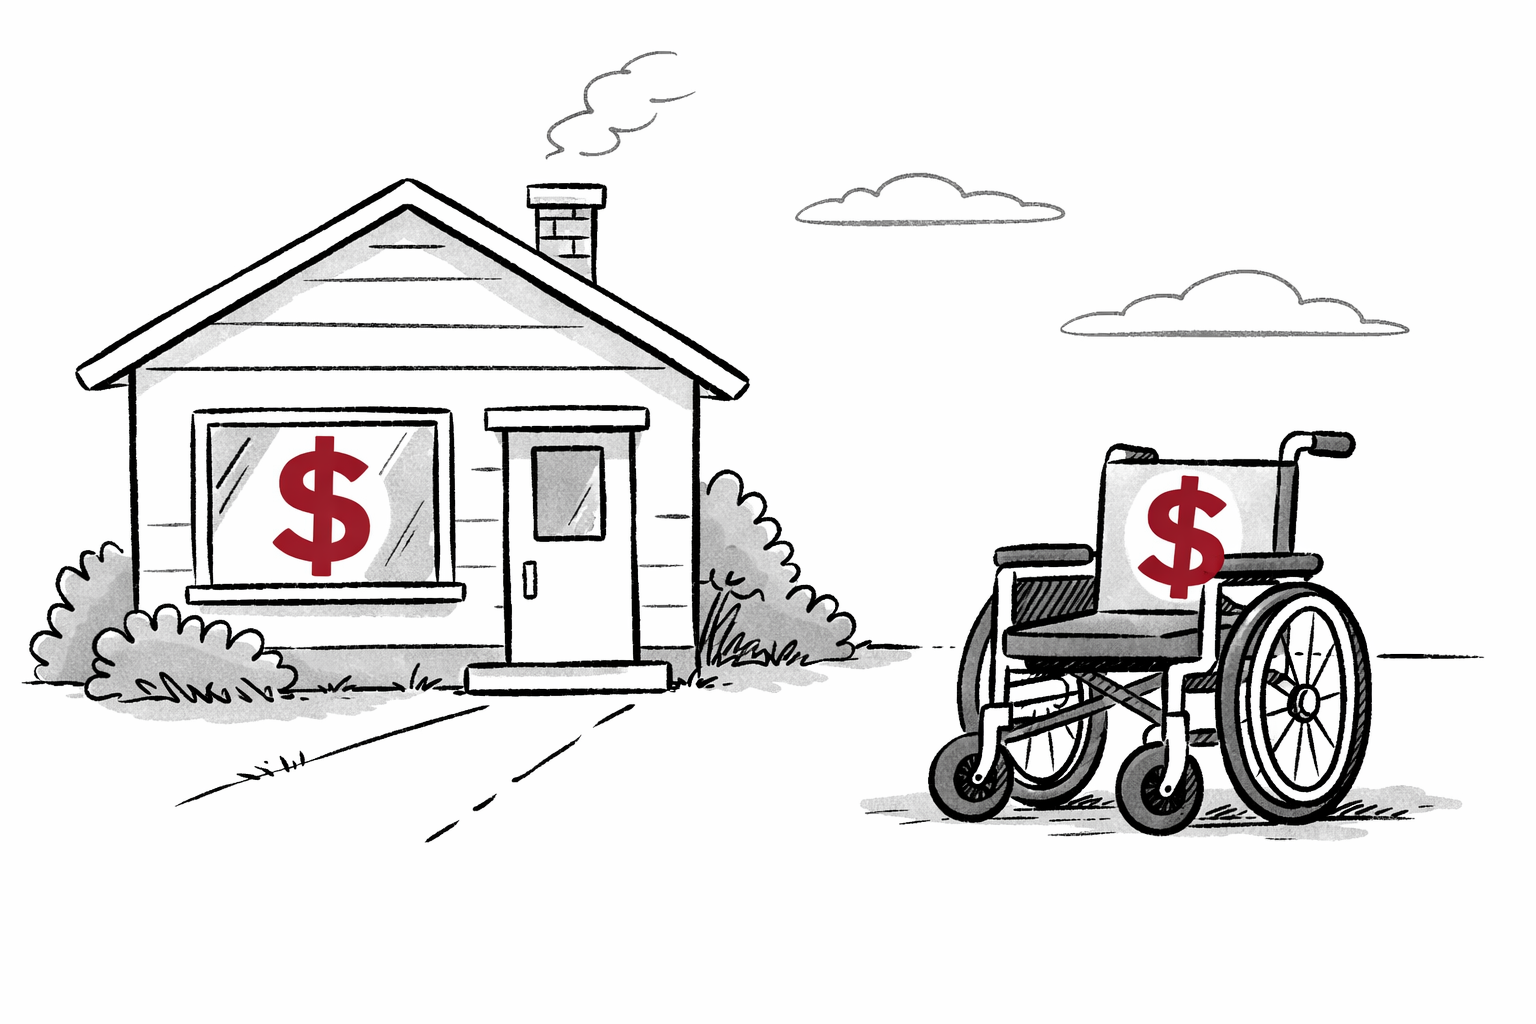

It’s often hard for advisors to bring up long-term care insurance. One simple way to start is by anchoring it to something clients already understand: homeowner’s insurance.
What to know
- Familiar anchor: Most clients already accept homeowner’s insurance as protection against a large, uncertain loss
- Comparable premiums: Both homeowner’s and LTC policies can carry annual premiums in the $5k–$10k range
- LTC has higher probability: Over 70% of people age 65+ will need some form of long-term care
- Similar severity: Both protect against large expenses, with care costs easily running into the hundreds of thousands
Planning implications
Many advisors treat LTC as a discretionary conversation, which leads clients to evaluate it that way. That framing misses the point. I find that clients respond to LTC planning when it’s positioned alongside something familiar, like homeowner’s insurance. The goal becomes protecting against a meaningful financial loss, not optimizing returns.
When to raise this with clients
- When a client says they plan to self-fund future care costs
- When there is clear sticker shock on initial premium quotes
Bottom line
Positioning LTC alongside homeowner’s insurance reframes it from optional spending to core risk management.
Client resources: I publish short videos and articles explaining long-term care concepts for your clients.
Work together: I'm a long-term care specialist. In addition to articles like these, I help financial professionals evaluate coverage options for clients. Reply or schedule time to refer a client or discuss a case.
Best,
Jesse Vickey
Long Term What?
P.S. If this was forwarded to you, sign up to receive future emails.