Cristie,
Your long-term care insurance quotes are ready.
First, please watch this short video I made for you:
🔎 Your quotes
I've provided three quotes, each with an initial benefit of $6,000 per month, to allow for an apples-to-apples comparison.

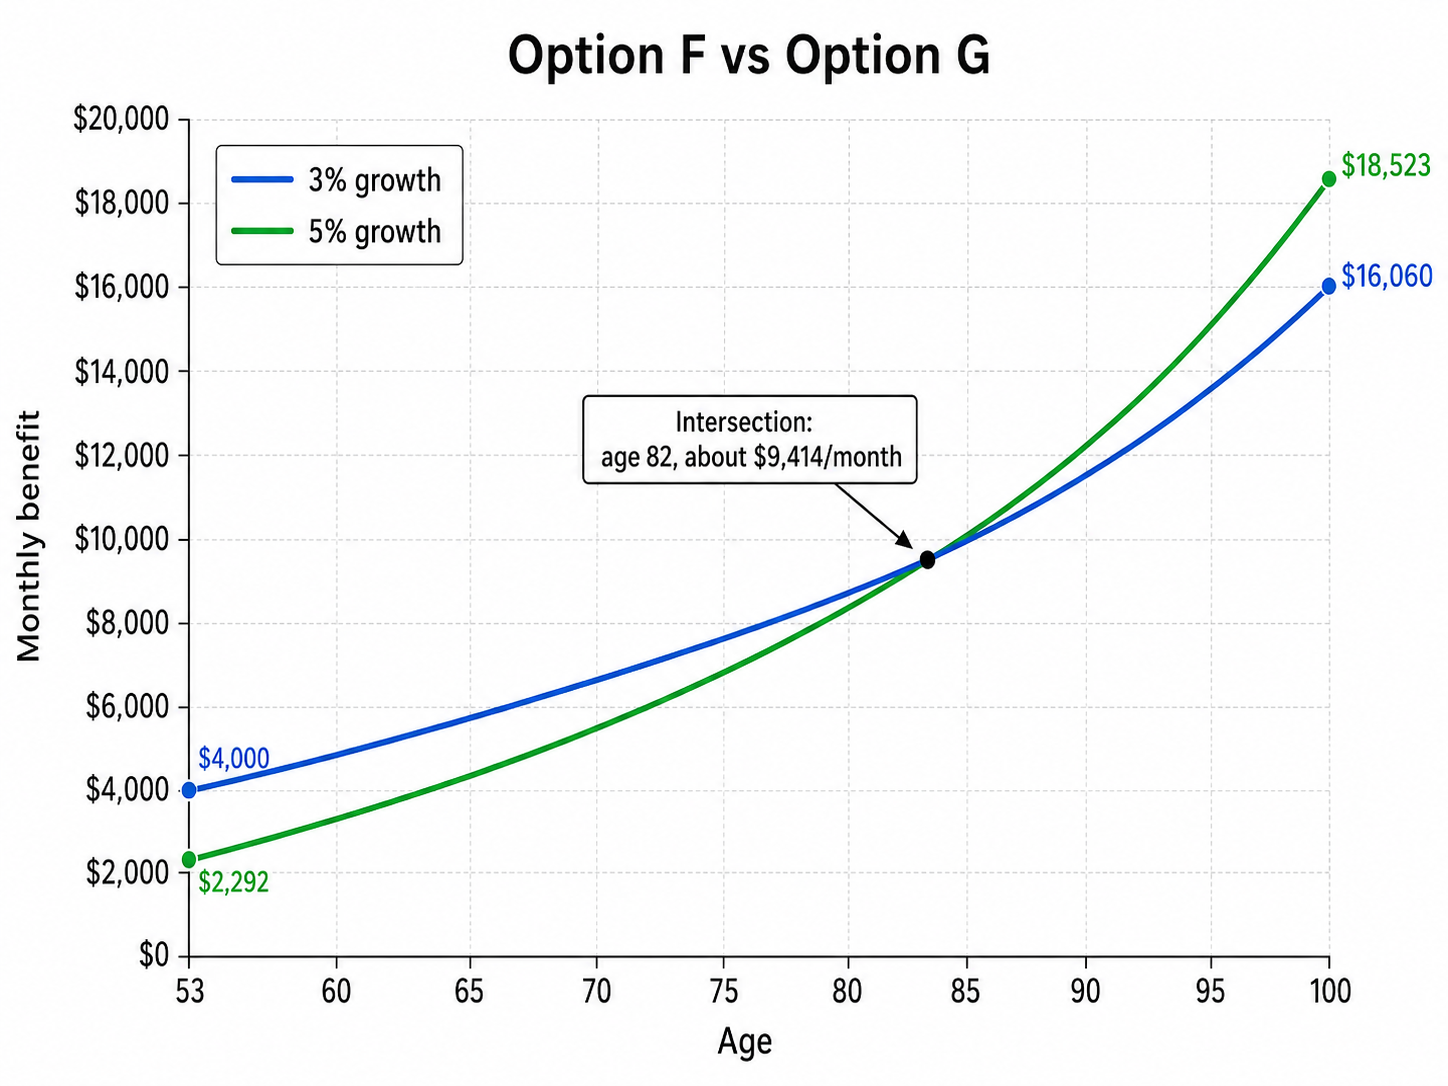
Options F and G differ in benefit growth: 3% vs. 5%. With the premium held constant, the tradeoff for 5% growth is a lower initial benefit. By about age 82, the 5% option catches up and then provides the higher monthly benefit.
🧐 My notes
All three options are strong and among the most popular policies on the market.
Option A: This five-year traditional policy from NGL offers lower premiums in exchange for no benefit to heirs. Benefits are paid as reimbursement for eligible care expenses.
Option B: This five-year hybrid policy from Nationwide pays benefits in cash and provides a $144,000 benefit to your heirs if you never need care.
Option C: This is the same policy as Option B, but with higher premiums in exchange for seven years of benefits and a larger total benefit pool.
These policies provide lower annual benefits than the projected cost of care, but you can bridge the gap using personal savings and Social Security. For most people, the goal is to secure meaningful coverage rather than insure every dollar of potential care costs.
You can also reduce your benefits to fit your budget. For example:
- Shorten the benefit period (e.g., to 4 years)
- Reduce the initial benefit (e.g., to $5k/month)
- Reducing the premium by 25% would generally reduce the benefits proportionally.
👉🏻 Next steps
Reply to my email or text with feedback or schedule time on my calendar to review these options together.
Alternatively, complete this longer health pre-screen form (15 minutes) for more clarity on your options. I’ll share your answers with insurers without your name attached to get informal feedback. This helps identify which policy is the best fit and avoids the risk of a formal decline.
Thanks,
Jesse
P.S. Still learning? See our popular blog or YouTube channel.