August and Ann,
Your revised long-term care insurance quotes are ready.
Please watch this short video first:
🔁 Revised quotes
I selected these three Nationwide CareMatters Together options based on your preferences for cash benefits and a shared pool of benefits. I chose Nationwide because it is among the most competitive hybrid policies offering joint coverage for couples who do not want to pay for lifetime benefits.

🧐 My notes
Thanks for speaking with me about your preferences of long-term care policies as you plan your move to Illinois.
Benefit growth
To compare 3% (option A) versus 5% (option B) benefit growth, I graphed both options using the same premium of $2,084 per month for 10 years.
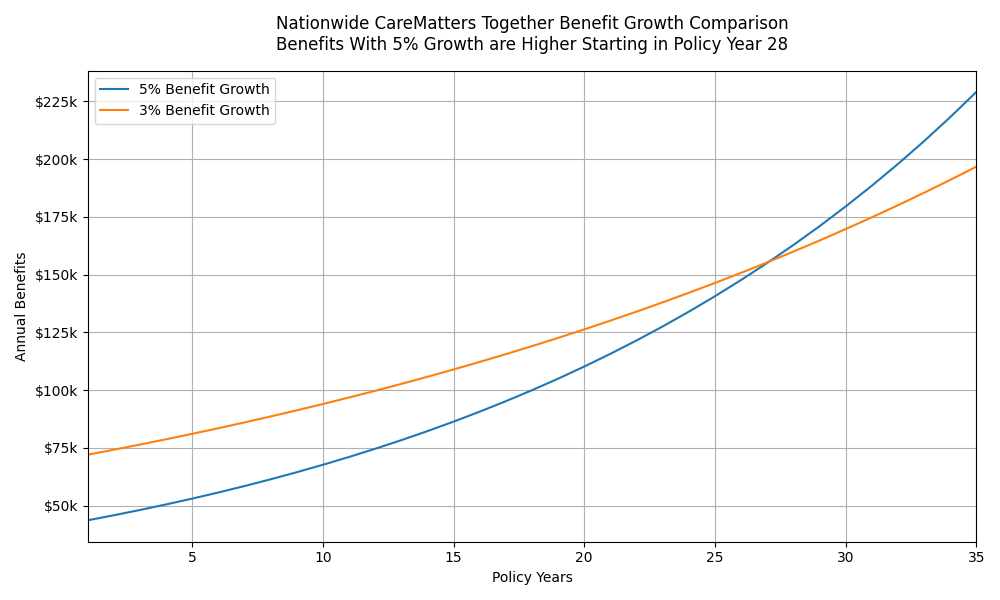
As the chart illustrates, the 3% growth option provides higher annual benefits for the first 27 policy years. The 5% growth option does not surpass the 3% option until policy year 28, when you would both be in your 90s.
Because long-term care claims often begin well before that point, I believe the 3% growth option is a better choice. You'll receive higher benefits for most of your life.
Nationwide CareMatters Together
This is a popular policy for several reasons:
- Benefits are paid as cash indemnity, allowing you to use them to pay informal caregivers, including family members.
- You share an eight-year pool of benefits, giving you flexibility if one spouse needs significantly more care than the other.
- If benefits remain unused, your heirs receive the remaining death benefit after both of you pass away.
- Even if you use most or all of your long-term care benefits, the policy guarantees a minimum death benefit equal to 10% of the original amount. For example, if your death benefit is $216,000, your heirs would still receive at least $21,600.
- Like most policies, benefits begin after a 90-day elimination period. However, once you qualify for benefits, CareMatters Together reimburses you retroactively for covered expenses incurred during those first 90 days.
- If either of you goes on claim, premiums are waived while that person is receiving benefits.
- Premiums are guaranteed and cannot increase.
- Click below for a Nationwide CareMatters Together brochure for additional details:
Partnership policies
I did not include any traditional long-term care policies because of your preference for cash benefits, which traditional policies do not offer.
As we discussed, if you wait until after your move to Illinois, you could consider an Illinois Partnership policy. Because Massachusetts does not participate in the Partnership program, this option is not currently available to you. Partnership policies can help protect a portion of your assets if you exhaust your policy benefits and later need to qualify for Medicaid while receiving care at a facility that accepts Medicaid.
The tradeoff is that waiting creates the possibility that a future change in health could affect your eligibility for coverage or limit your available options.
Other notes
- I included both 5-year and 10-year payment options. If you prefer, I can also illustrate a single-pay option.
- Your coverage follows you wherever you live in the United States, including Illinois.
- Policy A provides an initial monthly benefit of $6,000, while Policies B and C provide $7,500 per month. These amounts can be customized, so you can choose any starting benefit between those figures.
👉🏻 Next steps
I'd like to ask both of you to complete a more detailed health pre-screen form (approximately 15 minutes). I’ll share your answers with Nationwide and other insurers without your name attached to get informal feedback. This helps identify which policy is the best fit and avoids the risk of a formal decline.
Thanks,
Jesse
P.S. Still learning? See our our popular blog or YouTube channel.